Commercial real estate (CRE) lending can expose banks and credit unions to changing market conditions. Effective CRE risk management helps lenders monitor concentrations, evaluate potential vulnerabilities, and make informed decisions about their portfolios.
What does CRE risk management involve?
The commercial real estate landscape is constantly changing. Effective CRE risk management at a bank or credit union involves adapting to changing market conditions. This includes setting and periodically adjusting concentration limits for different products and markets.
Managers and loan officers focused on short-term earnings may resist efforts to reduce exposure levels. However, when CRE lending is a significant revenue source, failing to adjust concentration levels in response to warning signs can lead to excessive loan losses. The severity of those losses depends on loan underwriting quality and the depth of a downturn in the CRE market or specific segments of it.
The following indicators and examples can help lenders evaluate CRE concentration risk and manage it using CRE stress testing.
Market conditions can signal potential CRE risk
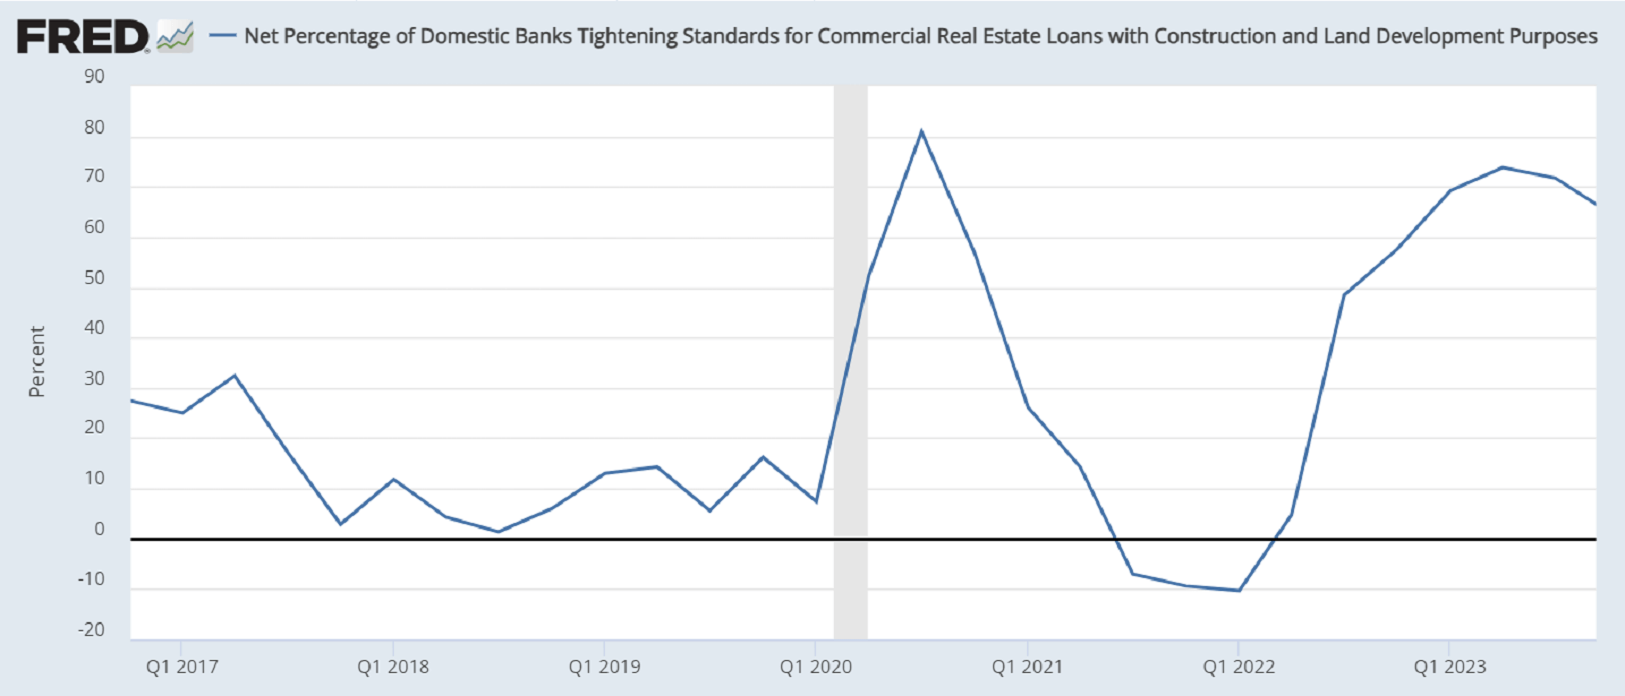
Construction companies often face pressure from financing costs, labor availability, project expenses, and timelines. Monitoring project budgets, inspections, and loan draws can help lenders track progress and identify issues that could affect repayment. In addition to monitoring individual construction projects, lenders should track broader credit conditions that may affect the CRE portfolio. Recent national data provide context for those conditions, although trends may vary by market. The Federal Reserve’s July 2026 Senior Loan Officer Opinion Survey found that banks generally reported easier CRE lending standards and basically unchanged demand.
The FDIC’s second quarter 2026 Quarterly Banking Profile reported that past-due and nonaccrual rates for non-owner-occupied CRE loans eased during the quarter, particularly among larger institutions. At banks with more than $250 billion in assets, the rate declined to 3.08%, below its 4.99% peak in the third quarter of 2024 but above the 0.59% pre-pandemic average. Across the industry, the volume of past-due and nonaccrual non-owner-occupied CRE loans fell 8.9% from the prior quarter.
These figures provide industry context; lenders should assess their own portfolios and markets.
Vacancy, absorption, rents, lease terms, available inventory, construction starts, and permits can also help lenders assess conditions by property type and geographic market. The OCC’s Commercial Real Estate Lending handbook describes these as examples of useful market data.