Looking for 360 View?

You're in the right place. 360 View is now part of Abrigo.
Read the press release

AI and generative AI use cases in banking: 6 real-world examples

Mary Ellen Biery
October 15, 2026
0 min read

A couple of years ago, many banks and credit unions were still cautious about introducing generative AI into day-to-day workflows. That conversation has changed. Financial institutions are increasingly moving beyond experimentation to identify practical applications for GenAI, establish governance, and determine where the technology can improve productivity, decision-making, and customer or member service. 

Generative AI use cases are increasing 

As adoption expands, the question for many institutions is where GenAI creates measurable value in banking, which use cases make sense to pursue first, and what controls are needed to use it responsibly. 

As adoption expands, the question for many institutions is where GenAI creates measurable value in banking, which use cases make sense to pursue first, and what controls are needed to use it responsibly.

Recent research reflects that shift. An EY-Parthenon survey of retail and commercial banks found that 47% of respondents had fully rolled out GenAI applications in 2025, up from 10% in 2023. Sixty-one percent also reported substantial impacts from their GenAI deployments.

What is generative AI for banking?

Generative AI creates new content or responses based on patterns and information in the data available to it. In a bank or credit union, that can mean summarizing documents, answering questions about policies, drafting narratives, interpreting institutional data, assisting employees, or supporting customer/member interactions. 

How is generative AI different from predictive AI?

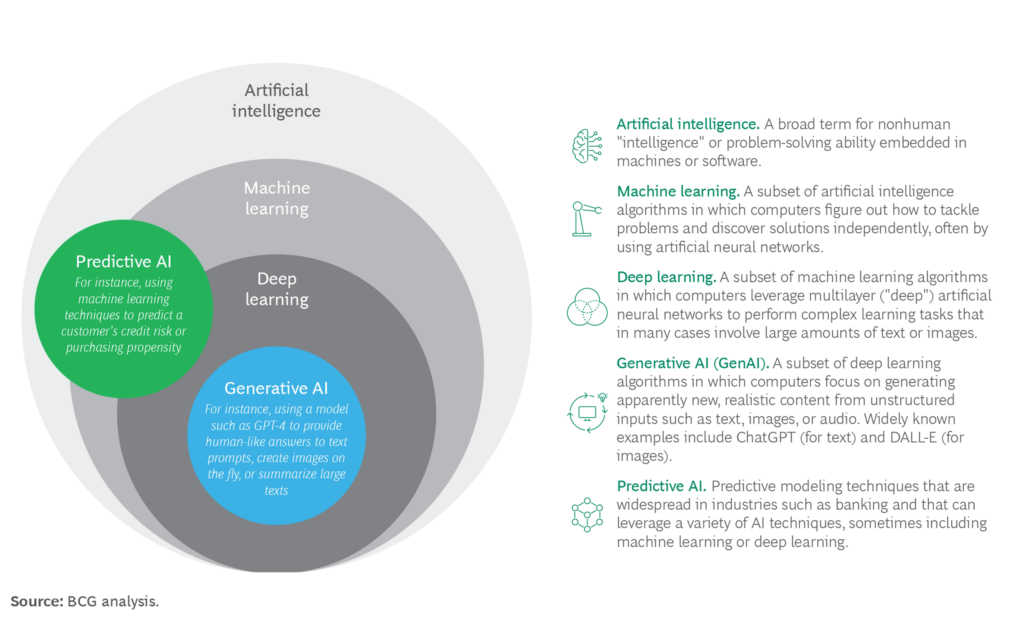
Predictive AI analyzes data to identify patterns, classify information, estimate risk, or predict outcomes. Banking examples include fraud risk scoring, probability-of-default models, pricing, and risk monitoring. 

Generative AI creates or synthesizes content based on information it can access. Banking examples include summarizing loan documents, creating draft narratives, answering employee questions about policies, or generating responses based on institutional data. 

Boston Consulting Group graphic on artificial intelligence and generative AI from a piece on genAI use cases

Banks and credit unions increasingly use both forms of AI, sometimes within the same workflow. The following examples focus specifically on how institutions are applying generative AI. 

An example of a use case for predictive AI is Signature Bank of Georgia’s addition of AI-driven check fraud detection software that finds fraud faster. The software evaluates over 20 unique features of each check coming in to provide financial institutions with a risk score indicating the probability of a fraudulent check.

Another example of using predictive AI is small business lending software that incorporates AI-driven lending intelligence. Abrigo Small Business Lending Intelligence powered by Charm provides loan rating risk scores, the probability of default, and how the score was calculated. The engine leverages self-learning AI to continuously monitor a wide range of current and historical data, loan performance, accounting, and macroeconomic data from more than 1,200 institutions.

Predictive AI use continues to expand in financial institutions. But in recent years, generative AI has seen much fanfare – and investment.

What concerns are there with generative AI use in banking?

One reason banking professionals have heard so much enthusiasm around using generative AI is its potential financial impact on the industry. 

In “Capturing the full value of generative AI in banking,” McKinsey estimates that GenAI could add the equivalent of between $200 billion and $340 billion in value annually across the banking industry. That’s equivalent to 9% to 15% of operating profits, the report notes. The greatest absolute gains forecast, largely from increased productivity, are tied to corporate and retail banking. 

As generative AI adoption expands, banks and credit unions continue to have legitimate concerns about how the technology fits within a regulated environment. Financial institutions must consider whether a use case can improve a process, along with the data, controls, oversight, and technology needed to use it responsibly. 

Financial institutions have several reasons to approach generative AI carefully. Three areas deserve particular attention:

1. Customer trust, privacy, and information security

Generative AI creates additional considerations around how sensitive information is handled. Financial institutions should understand what data can enter a GenAI system, where that information is stored, who can access it, whether it can be used to train underlying models, and how customer and institutional data is protected. Clear policies and access controls can help reduce inappropriate use and support customer trust.

2. Regulatory compliance, accuracy, and human oversight

Banks and credit unions remain responsible for decisions and communications supported by AI. Because GenAI can produce incomplete or inaccurate information, institutions need processes for reviewing outputs, documenting appropriate uses, and escalating issues when necessary. Explainability may also be important when AI supports decisions subject to regulatory requirements. Clear human oversight helps ensure employees understand when an output requires additional review and who remains accountable for the final decision.

3. Technology, staffing, and governance resources

Effective use of GenAI depends on the institution’s data infrastructure, technology, vendor relationships, internal ownership, policies, employee training, and capacity for ongoing oversight. Financial institution leaders should also consider the AI capabilities available through existing technology providers as they determine where additional solutions and resources may be appropriate.

Despite these considerations, financial institutions are already using generative AI in targeted ways to improve customer experiences, support employees, and increase efficiency. Examining those use cases can help banks and credit unions identify where the technology may provide value within their own operations. 
How are banks and credit unions using generative AI?

Here’s a quick look at some generative AI use cases being employed at banks and credit unions:

1. GenAI use case for understanding financial institution data

Southwestern National Bank used to spend hours gathering data and working in spreadsheets to create a geographic concentration report for the OCC examiners. Using Abrigo Connect, a business intelligence solution, the bank can use natural language when searching for data to help with regulatory examinations, board reporting, or weekly management and risk reporting. Now, Southwest National uses Connect to generate a report in seconds to show examiners the loan concentrations across its markets. The same solution can help Southwestern examine efficiency within operations and improve credit and portfolio risk monitoring.

2. GenAI use case for resolving financial institution member or customer needs faster

Pentagon Federal Credit Union (PenFed) provides the status of loan applications, product and servicing information, and technical support to members nearly 40,000 times a month using a Salesforce Einstein-powered chatbot. The chatbot generates answers to members' questions and now resolves 20% of member cases on first contact, according to a report on CIO.com. The reduced pressure on its call center has allowed PenFed to cut its time to answer calls by a minute, to just under 60 seconds, despite increased membership.

3. GenAI use case for fostering relationship banking

Abrigo client BAC Community Bank in Stockton, Calif. ($800m deposits) uses an app that answers customer questions and matches them with a BAC banker as their assigned contact.

4. GenAI use case for sniffing out fraud in emails and instructions

JPMorgan is reportedly using large language models to fight fraud and other attacks embedded in email and other financial communication. Its technology can detect signals for fraudulent emails or fraudulent instructions for a wire. MasterCard is reportedly trying to better protect from fraud its cardholders and the financial institutions using its network with its proprietary generative artificial intelligence model. The GenAI model uses the 125 billion transactions on MasterCard’s network each year to identify fraudulent patterns so financial institutions identify more fraud while spending less time assessing specific transactions.

5. GenAI use case for training employees and making them more productive

SouthState Bank, another Abrigo client, trains its enterprise version of ChatGPT only on bank documents and data. No customer data is fed into the system and it's not available to anyone outside the bank, which has $45 billion of assets. Employees are asking the system questions about the bank's 400-page commercial loan policy and 600-page branch policies and procedures. A new teller who needs to reissue an ATM card can ask the system how to do it; employees summarize regulatory documents or sets of policies; marketers create copy and bankers compose emails with it. "In our couple months of rolling it out, we get a five to eight X boost in productivity just by saving time," Nichols told American Banker. "It normally takes an employee 12 to 15 minutes to figure out the correct answer. That gets reduced to seconds."

6. GenAI use case for resolving bank transaction/fraud disputes

Financial institutions have been beta testing Salesforce’s genAI-powered Transaction Dispute Management in “human in the loop” or “copilot” mode with human agents. Fraud dispute resolution is often a huge expense for banks and credit unions and one that causes a lot of client frustration, Tech Target notes in a recent report. The technology is a bot that helps with dispute acknowledgment, case opening, resolution, and closure by invoking policies, procedures, history, and knowledge bases. The goal is consistency and transparency in resolving transaction disputes and improving retention by resolving employee frustrations.

See how Southwestern National Bank's Chief Credit Officer can quickly access past dues, upcoming maturities, and a report showing geographic loan concentrations.

Keep me informed Read the story

How should a community bank choose a generative AI pilot? 

A successful GenAI pilot should start with a focused use case that offers clear business value, manageable risk, and results the institution can measure. 

  • Business value: What measurable problem does this use case solve? 
  • Baseline: How much time, money, manual work, or risk does the current process involve? 
  • Implementation effort: What data, integrations, training, and vendor support are required? 
  • Risk: Does the use case affect customers, regulated decisions, sensitive data, or compliance obligations? 
  • Time to value: Can the institution measure a meaningful result within a controlled pilot? 
  • Human oversight: Who reviews the output and remains accountable? 

What should banks measure during a GenAI pilot? 

Depending on the use case, establish the baseline before implementation, then measure: 

  • Staff time per task  
  • Processing or turnaround time  
  • Number of manual steps  
  • Error or rework rates  
  • Volume handled per employee  
  • Customer/member resolution time  
  • Fraud losses identified or avoided  
  • Adoption and employee usage  
  • Cost of the existing process versus the pilot.

Turning generative AI use cases into measurable value

Generative AI will continue to attract investment dollars and attention from financial services companies and other industries as businesses continue efforts to use technology to improve efficiency, products and services, and performance. Understanding what genAI is, how credit unions and banks are using it now, and how to tap into additional resources on genAI will help leaders explore the potential for it within their own financial institutions.

About the Author

Mary Ellen Biery

Senior Strategist & Content Manager
Mary Ellen Biery is Senior Strategist & Content Manager at Abrigo, where she combines financial journalism, original research, and SEO/AEO strategy to create authoritative content that helps financial institutions manage risk and pursue growth. A former Dow Jones Newswires equities reporter, her work has appeared in The Wall Street Journal,

Full Bio

About Abrigo

Abrigo enables U.S. financial institutions to support their communities through technology that fights financial crime, grows loans and deposits, and optimizes risk. Abrigo's platform centralizes the institution's data, creates a digital user experience, ensures compliance, and delivers efficiency for scale and profitable growth.

Make Big Things Happen.